
Editor’s note, October 2026 — A 2021 announcement of intent. Regulation did follow, though not quite in the shape described here — the decisive measure turned out to be a payments rule rather than a new regulator. What was actually built is below the original article.
Commerce Minister Tipu Munshi on Wednesday said the government will set up an e-commerce regulatory body to monitor the sector.
He also noted that there will be a detailed e-commerce law passed and enforced soon, alongside establishing a central complaint cell.
"Legal actions as per the current law will be taken against those companies who have cheated customers," he said.
He made the remarks after presiding over a meeting at the commerce ministry to review the recent problems in the country's digital e-commerce business and policy-related decisions regarding the sector.

The minister said that the Digital Security Act and Money Laundering Act will be amended to ensure legal action against fraudulent companies.
Tipu Munshi noted that there were some legal complexities about refunding customers of Jubok and Destiny group by using those companies' assets.
"The law minister has been instructed to solve the issue," he added, saying that the government cannot shut down the entire e-commerce sector for 10-12 companies.
According to the minister, transactions worth Tk6,000 crore took place in the e-commerce sector before the introduction of the escrow service on 4 June.
Following its introduction, products worth Tk400 crore have been ordered through the service and Tk200 crore has been transacted.
The minister said that companies like Evaly and Alesha Mart wasted a lot of their assets on advertisements and sponsorships.
"We will try to ensure that these companies cannot cheat customers [any further]. Every company must obtain a unique Business Identification Number from the commerce ministry," Tipu Munshi said.
Regarding the finance minister's comment on the commerce ministry's responsibility for frauds committed by e-commerce platforms, Tipu Munshi said, "We have arranged the meeting because we have obligations. We [commerce ministry] don't want to escape those obligations."
Home Minister Asaduzzaman Khan Kamal, Law Minister Anisul Huq, Information Minister Hasan Mahmood, Commerce Secretary Tapan Kanti Ghosh, Competition Commission Chairman Mofizul Islam, Digital E-Commerce Cell Head and WTO Director General (Additional Secretary) Hafizur Rahman, Deputy Secretary Mohammad Saeed Ali and other senior officials were present at the meeting.
Earlier, Commerce Minister Tipu Munshi requested people to control their urge of buying products at low prices from e-commerce platforms to prevent fraudulent incidents like those by Evaly and Eorange.
Evaly received advance payments by luring people with heavy discounts on products on its site and promising delivery within 7-45 days. Many buyers, however, are yet to receive the items they ordered.
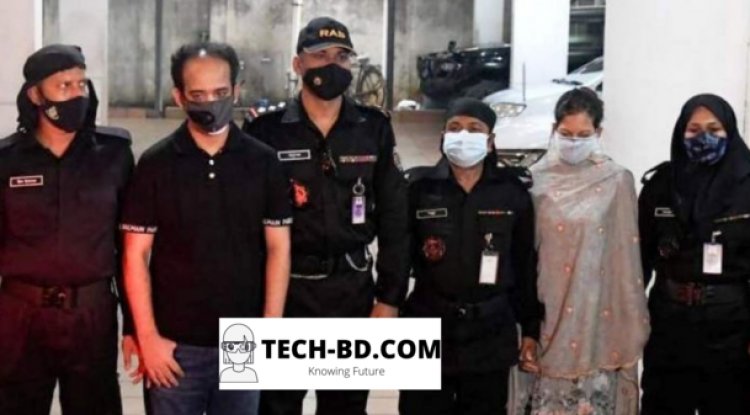
The Rapid Action Battalion recently arrested the CEO and chairman of Evaly following a case filed by a customer on allegation of money embezzlement. Later, two more cases were filed against the couple.

Besides, another e-commerce platform, Eorange, followed the same business model. They were not delivering products to customers or not returning the money paid against the orders over the past few weeks. Top officials of the controversial online merchants are already in jail.
What was actually built
The announcement above promised a regulatory body. What changed the sector was narrower and arrived through the central bank rather than a new institution.
Bangladesh Bank was placed between buyer and seller. Advance payments made to e-commerce merchants are held and released only after the customer receives the goods, with delivery required within five to ten days. The framework was set out in the Guidelines for Merchant Acquiring and Escrow Services 2023, which required banks and payment service providers acting as merchant acquirers to adopt onboarding policies for the platforms they serve.
Why a payments rule worked where a regulator might not have
The lesson generalises. A regulator supervises conduct and acts after a failure; an escrow requirement changes what is physically possible. A platform that never holds the customer's money cannot spend it on earlier orders, which is the specific mechanism every one of these collapses relied on.
It also put the obligation on the banks and payment providers, which are already licensed, already examined, and far fewer in number than the merchants. Supervising a few dozen acquirers is tractable in a way that supervising thousands of online sellers is not.
What it did not fix
Recovery for the people already affected. Once the commerce ministry asked Bangladesh Bank to start returning funds, it emerged that no agency held a dependable record of which companies had been sued, and refunds stalled on that gap. A separate High Court inquiry was ordered into which officials' negligence had allowed the schemes to operate.
The lesson is an uncomfortable one for any market in this position: rules written after a collapse protect the next cohort of customers, not the one that paid for the lesson.